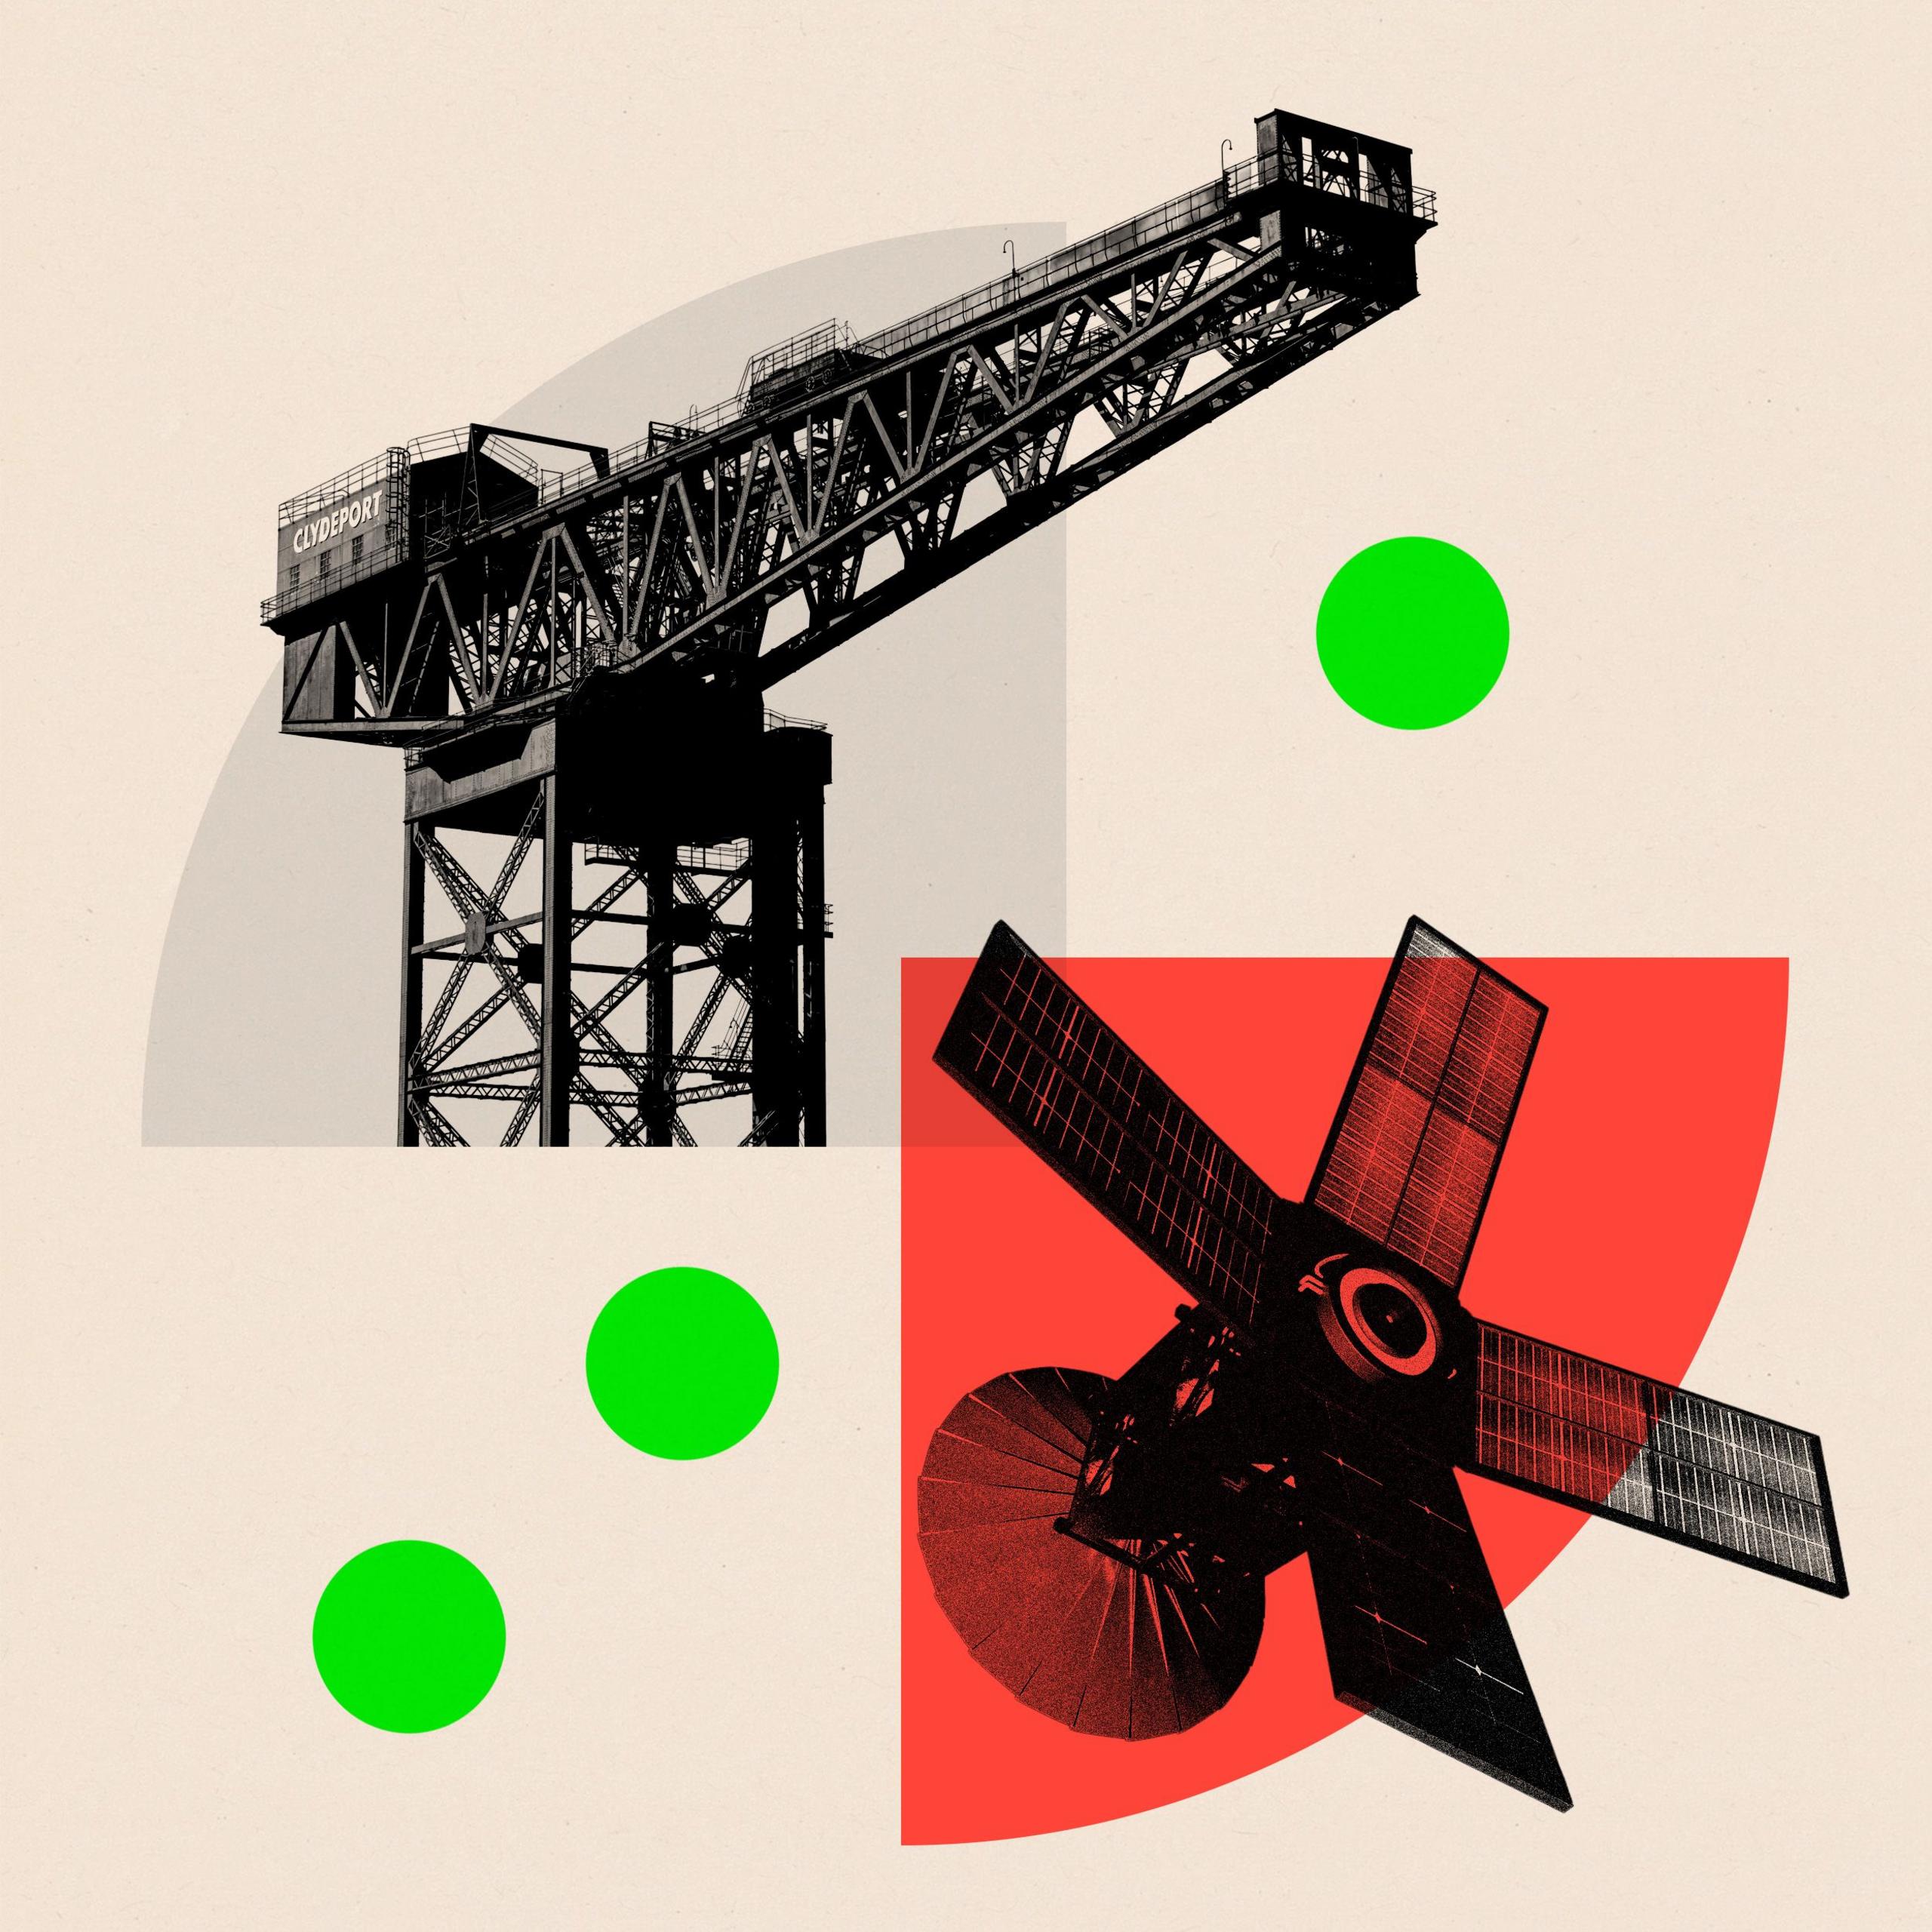
Glasgow, once famed for shipbuilding, now hosts Europe’s largest micro‑satellite cluster, home to companies such as Clyde Space, AAC Microtec and Spire.
The rise began in 2005 when engineer Craig Clark founded Clyde Space, leveraging an oil‑rig‑style supply chain and a partnership with the University of Strathclyde to build CubeSats. The city now produces more small satellites than any other European city, driving a £335m industry and 2,800 jobs in 2022‑23.
CubeSats, the size of a Rubik’s Cube, are modular and can be stacked with sensors, cameras and communications gear. Their data underpins navigation, weather forecasting, maritime traffic and national security, giving governments a reason to invest heavily in domestic production.
Governments across Europe are pumping billions into space. Germany plans a €35bn defence‑space programme, while Finland’s ICEYE raised over €1bn in a recent round. These injections signal a shift from grant‑led development to procurement‑led growth, favouring firms in countries with strong government contracts.
Industry voices warn that Scotland’s advantage could erode if funding follows the money. While companies like Alba Orbital have relocated headquarters to the US, the city still builds the most satellites per square kilometre and hosts key suppliers.
To stay competitive, policymakers need to turn procurement into a growth engine rather than a grant‑based safety net. A government contract delivers immediate revenue, a track record and a pathway to other markets.
The Manchester‑based perspective stresses that certain capabilities—such as domestic satellite manufacturing—are strategic insurance in crises, but they come at higher costs and may necessitate duplication of allied expertise.
Glasgow’s rivals are expanding too. Spire has opened manufacturing in Munich, and Skyrora celebrates a fire‑test success last month, hinting at a future in Russian‑style launch complexes.
Yet the city’s unique mix of talent, suppliers and institutional research offers a type of depth difficult to replicate elsewhere. New entrants such as Simera Sense are opening production lines in Dalmarnock, signalling that the industry still attracts investment.
The ultimate test will be whether Glasgow can translate its manufacturing prowess into a comprehensive, end‑to‑end space sector that secures domestic demand and exports to a global market. If it does, it may turn the city into a fully integrated space hub; if it does not, the momentum could stall and talent may migrate, pulling the city down a competitive path that once drove global shipyards.